Finance
Mygreenbucks Net Jones: What You Need to Know


The search phrase mygreenbucks net jones usually comes from people trying to answer two connected questions: what exactly is MyGreenBucks.net and who is Kenneth Jones in relation to the website?
That sounds simple. In practice, the answer requires a little care because MyGreenBucks.net contains finance-related content attributed to Kenneth Jones while different pages and third-party articles describe his role in different ways. The most useful approach is therefore to separate what can be seen directly on the website from claims that are harder to verify.
What Is MyGreenBucks.net?
MyGreenBucks.net currently presents itself primarily as a financial information website. Its homepage covers subjects including personal finance, money management, cryptocurrency, and business, while its About page says its purpose is to help readers make and manage money through informational content.
The site includes sections such as:
- Finance For Life
- Managing Money
- Cryptocurrency
- Business
- Latest financial and consumer topics
It also publishes articles under multiple categories and prominently displays Kenneth Jones as the author of numerous posts. Current pages indexed on the website show his byline across cryptocurrency, money, and business content.
That makes one point relatively clear: Kenneth Jones is publicly presented as a contributor or author associated with MyGreenBucks.net.
What becomes less clear is whether he should also be described as the founder, owner, financial adviser, executive, or creator of the platform.
Mygreenbucks Net Jones Quick Facts
| Question | What Can Be Confirmed |
|---|---|
| What is MyGreenBucks.net? | A website publishing finance, money, crypto, business, and related content |
| Is Kenneth Jones associated with it? | Yes. Numerous articles display Kenneth Jones as an author |
| Is Kenneth Jones definitely the founder? | The site’s own published material is inconsistent on this point |
| Is MyGreenBucks.net a bank? | Its current public pages primarily present it as an informational website |
| Does the site offer financial content? | Yes |
| Should every financial claim be accepted automatically? | No. Important claims should be checked against independent authoritative sources |
| Is there a user area? | The site has a page labeled “Customer Cabinet,” although its publicly indexed content provides little detail about its purpose |
Who Is Kenneth Jones at MyGreenBucks?
Kenneth Jones is the name most closely connected with MyGreenBucks.net in search results.
On the current site, his name appears beneath many articles. A 2026 profile published by MyGreenBucks describes Jones as an author covering personal finance, sustainable investing, and lifestyle topics. That page says he joined MyGreenBucks in 2019 and previously worked as a financial analyst.
That description is important because it frames Jones primarily as an author.
However, an older article hosted on the same domain presents a considerably different story. It describes Kenneth Jones as the person who developed or founded MyGreenBucks.net and attributes extensive finance experience and academic credentials to him.
These differences are one reason searches for mygreenbucks net jones continue to generate confusion.
Is Kenneth Jones the Founder of MyGreenBucks.net?
It would be premature to state this as an independently established fact.
Some content published on MyGreenBucks.net describes Jones as the mastermind or creator behind the platform. Yet the site’s current About page does not name Kenneth Jones as its founder or identify a specific founder at all. Instead, it gives a general description of MyGreenBucks and its financial-content mission.
Meanwhile, the newer 2026 Kenneth Jones profile describes him as an author who joined the website in 2019.
For readers, this distinction matters.
There is a meaningful difference between:
- being an article author
- being an editor
- being a financial expert
- owning a website
- founding a company
- operating a regulated financial business
Those roles should not be treated as interchangeable without supporting evidence.
Why Is “Mygreenbucks Net Jones” Being Searched?
The keyword appears to reflect informational and verification-focused search intent.
People discovering the site may see the Kenneth Jones name repeatedly and naturally want to understand his connection with the platform.
Typical questions behind the search include:
- Who is Kenneth Jones?
- Does Kenneth Jones own MyGreenBucks.net?
- What does MyGreenBucks actually do?
- Is it a financial information site or a financial service?
- Can the site’s money advice be trusted?
- Are claims about Kenneth Jones independently verified?
- Is MyGreenBucks.net legitimate?
Answering those questions requires more than repeating promotional descriptions. Users need context that separates observable facts from unverified biography or marketing claims.
What Does MyGreenBucks.net Actually Cover?
The present homepage makes the site’s editorial direction fairly easy to identify.
Personal Finance
Readers can find material dealing with budgeting, household expenses, taxes, borrowing, and general financial decisions.
These topics may be useful as starting points for research. However, personal finance content should always be evaluated according to the reader’s country, financial circumstances, and applicable laws.
Cryptocurrency
MyGreenBucks.net also publishes extensively about cryptocurrency, exchanges, digital platforms, and related financial trends.
Crypto content deserves additional scrutiny because prices, regulations, platform conditions, and investment risks change quickly.
A useful article can explain a concept. It cannot remove market risk.
Business Topics
The platform includes articles for entrepreneurs and small-business readers covering matters such as employee onboarding, business debt, taxes, e-commerce, and revenue-related decisions.
Again, informational guidance should not automatically be treated as professional accounting, tax, or legal advice.
Is MyGreenBucks.net a Bank or Financial Institution?
Readers should be careful with this distinction.
The current MyGreenBucks About page describes a content-focused website designed to provide information about earning and managing money. It does not describe the website there as a licensed bank.
Some external pages and older online articles use terminology such as “digital banking,” “wealth management,” “financial platform,” or “earning platform.” Those labels can create a stronger impression than the site’s currently visible core content supports.
Before treating any website as a regulated financial institution, check for details such as:
- Full legal company name.
- Financial-services licence number.
- Responsible regulator.
- Registered business jurisdiction.
- Verifiable physical address.
- Clear terms covering the actual financial service.
- Transparent fees and withdrawal conditions.
A polished website alone does not establish regulated status.
Evaluating the Kenneth Jones Claims
This is where readers can apply a simple EEAT-style verification process of their own.
1. Separate the Byline From the Biography
Kenneth Jones appearing as an author is directly observable on MyGreenBucks.net.
Claims concerning employment history, degrees, professional licences, founding roles, or major career achievements require a different level of evidence.
A biography published by the same website can be informative, but it is still a first-party claim.
2. Look for Independent Evidence
For financially sensitive subjects, strong verification can include:
- regulator databases
- professional licensing records
- corporate filings
- university records
- established media profiles
- identifiable professional organizations
- primary financial documents
Several recent independent reviews have also questioned how much of the Kenneth Jones biography can be verified outside websites repeating similar narratives.
That does not prove that every claim is false. It means readers should distinguish verification from repetition.
3. Check Whether Different Pages Tell the Same Story
Consistency is an overlooked trust signal.
One MyGreenBucks article describes Jones as the figure who created the site. A newer profile says he joined MyGreenBucks in 2019 as an author.
There may be an explanation for that difference. Until one is clearly documented, readers should avoid turning either description into a stronger factual claim than the available evidence allows.
Website Transparency: What Readers Should Examine
Financial websites deserve a higher level of scrutiny than entertainment blogs because readers may make real money decisions based on what they read.
About Page
The MyGreenBucks About page explains the site’s general mission but provides limited detail about the legal organization or editorial team behind it.
For a casual publication, that may not be unusual. For readers using financial information, however, more transparency makes credibility easier to assess.
Terms and Conditions
The website maintains a Terms and Conditions page. It refers to MyGreenBucks using generic terms such as “Company” and states that the site’s information is not guaranteed to be complete or accurate.
That last point deserves attention.
It means users should independently verify material before making decisions involving investments, taxes, debt, cryptocurrency, or other high-impact financial matters.
Privacy Policy
The privacy policy explains that the site may collect information associated with comments, login activity, cookies, browser details, and user accounts where applicable.
Readers should review privacy policies before registering with any unfamiliar financial or rewards-related website.
A Practical Trust Checklist
Before relying heavily on MyGreenBucks.net or any similar finance website, run through this checklist.
- Verify the URL. Similar-looking domain names can belong to completely unrelated websites.
- Check publication dates. Financial rules and crypto information can become outdated quickly.
- Look at the author’s evidence. Credentials should be independently checkable when they influence the authority of financial advice.
- Follow original sources. Government agencies, regulators, tax authorities, banks, and primary documents are stronger evidence than another blog repeating the same claim.
- Understand the business model. Know whether a site earns money from advertising, affiliates, subscriptions, referrals, or financial products.
- Never confuse education with personalised advice. A general article does not know your income, tax position, debts, goals, or risk tolerance.
- Be cautious with guaranteed returns. Legitimate investing involves uncertainty.
- Do not pay unexpected withdrawal or release fees without verification. Requests for additional money deserve careful investigation.
- Protect personal data. Do not provide identity documents or financial credentials unless you understand who receives them and why.
Common Mistakes People Make When Researching MyGreenBucks
Assuming Search Rankings Equal Authority
A page ranking highly for mygreenbucks net jones is not automatically the most accurate source.
Search visibility and factual verification are different things.
Repeating the Same Biography Across Multiple Sites
If ten articles repeat the same story but all ultimately derive it from one unverified source, that is not ten independent confirmations.
Look for evidence created independently of the claim itself.
Mixing Up Similar Domains
Search results contain multiple websites using versions of the MyGreenBucks name.
Readers should pay close attention to domain extensions, hyphens, and spelling rather than assuming every similarly branded result belongs to the same organization.
Treating an Author as a Licensed Adviser
Writing frequently about finance does not automatically establish professional licensing.
If a decision requires regulated financial, tax, accounting, or legal expertise, verify the person’s qualifications for that specific service.
What Makes Financial Content Worth Trusting?
Good financial content should help readers understand not only what to do but also why, under what conditions, and where the information comes from.
Strong content generally includes:
- specific sources
- publication or update dates
- realistic risk discussion
- clear distinctions between facts and opinions
- named authors
- relevant credentials
- transparent commercial relationships
- corrections when information changes
The subject becomes particularly important when articles involve cryptocurrency, investments, loans, taxes, or claims about earning money online.
The greater the financial consequence of being wrong, the stronger the evidence should be.
Is Mygreenbucks Net Jones Legit?
There are really two separate questions hidden inside this wording.
Is MyGreenBucks.net a real accessible website? Yes. The site currently publishes financial, cryptocurrency, money-management, and business content and contains active pages including About, Terms, Privacy, and Customer Cabinet sections.
Are all online claims about Kenneth Jones and MyGreenBucks independently established? No. The publicly available material includes conflicting descriptions of Jones’s relationship with the website, so readers should avoid assuming that every biography, founder claim, credential, or promotional description has been independently confirmed.
This does not justify automatically labelling the entire website a scam.
It does justify applying normal due diligence before relying on it for significant financial decisions.
How to Use MyGreenBucks Content More Safely
The most sensible way to approach a website like MyGreenBucks is as a starting point rather than a final authority.
For example, if an article discusses taxes, confirm important rules through the relevant government tax agency.
If it discusses an investment product, review the issuer’s official documents and the appropriate financial regulator.
If it reviews a cryptocurrency exchange, independently examine its security record, licences where applicable, fees, withdrawal policies, and current user terms.
This approach gives readers the benefit of accessible educational content without outsourcing important decisions to a single publisher.
Frequently Asked Questions
What does mygreenbucks net jones mean?
It is a search phrase connecting the MyGreenBucks.net website with Kenneth Jones, a name that appears frequently as an author and in articles discussing the platform.
Who is Kenneth Jones from MyGreenBucks?
Kenneth Jones is presented on MyGreenBucks.net as an author covering financial and related subjects. Some older pages additionally describe him as a founder or central figure behind the platform, while a newer profile says he joined MyGreenBucks in 2019.
Is Kenneth Jones the owner of MyGreenBucks.net?
The publicly reviewed pages do not provide enough clear, independently verified evidence to state ownership as a confirmed fact.
What type of website is MyGreenBucks.net?
Its current public-facing content is primarily focused on financial information, money management, cryptocurrency, business, and related consumer topics.
Is MyGreenBucks.net a bank?
Its current About page describes an informational money-focused website rather than identifying MyGreenBucks as a licensed bank.
Can I trust financial articles on MyGreenBucks.net?
They can be used for general research, but important financial claims should be verified through authoritative primary sources. The site’s own terms state that it does not guarantee the completeness or accuracy of its information.
Why are there different stories about Kenneth Jones online?
Different articles describe his role differently. Some call him an author while others describe him as the creator or founder of MyGreenBucks. That inconsistency is precisely why independent verification matters.
Final Verdict on Mygreenbucks Net Jones
The most reliable conclusion about mygreenbucks net jones is more nuanced than many search results suggest.
MyGreenBucks.net is an active website publishing material about personal finance, money management, cryptocurrency, business, and related subjects. Kenneth Jones is clearly associated with numerous articles on the site and is currently presented in a MyGreenBucks profile as an author.
Claims extending beyond that relationship deserve additional verification. In particular, descriptions of Jones as a founder, owner, highly credentialed financial professional, or central figure behind a broader financial platform should not be repeated as established facts solely because they appear across multiple SEO articles.
For readers researching mygreenbucks net jones, the best strategy is simple: use the site’s content for discovery, trace important statements back to primary sources, verify credentials independently, and apply extra scrutiny whenever your money or personal information is involved.
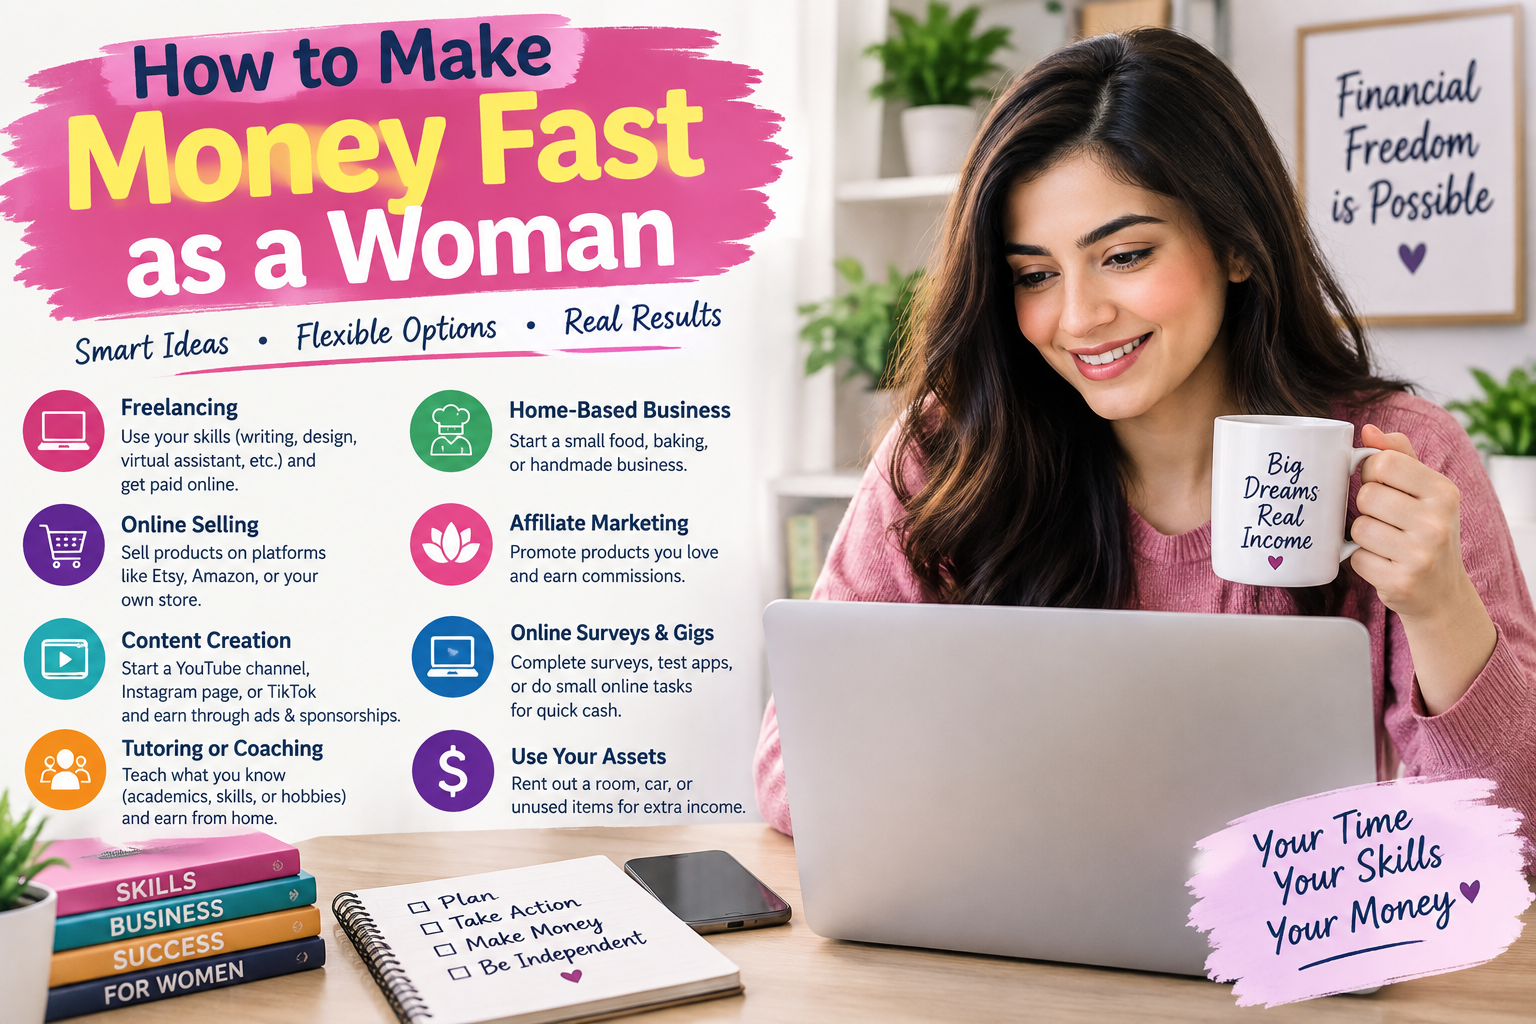
If you’re searching for how to make money fast as a woman, you probably don’t want another vague list telling you to “start a blog” and wait six months. You want realistic ways to bring in cash within hours, days, or a few weeks.
The fastest option usually isn’t building a new business from scratch. It’s monetizing something you already have: unused belongings, available time, existing skills, transportation, professional knowledge, or access to local demand.
This guide breaks down the fastest legitimate options, what each requires, and how to avoid turning an urgent need for money into an expensive mistake.
Quick facts
Fastest cash: Sell things you already own or offer a local service.
Best from home: Freelancing, virtual assistance, tutoring, user-generated content, and remote customer support.
Lowest startup cost: Cleaning, pet care, babysitting, freelance services, and selling unused items.
Best long-term potential: Freelancing, consulting, tutoring, specialized services, and content creation.
Biggest risk: Opportunities requiring upfront payments, inventory purchases, checks to deposit, or promises of guaranteed income.
What Is the Fastest Way for a Woman to Make Money?
For most people, the fastest legitimate money comes from one of three strategies:
- Sell an asset you already own.
- Provide a service someone needs immediately.
- Take paid work with an established marketplace or employer.
Selling a $200 unused appliance can be faster than completing twenty small online tasks. Likewise, finding one client who needs a $150 service may be more productive than joining several low-paying gig sites.
Start with the option that has the shortest distance between what you already have and what another person will pay for.
25 Legit Ways to Make Money Fast as a Woman
| Money-making idea | Typical speed to first money | Startup cost | Can be done from home? |
|---|---|---|---|
| Sell unused belongings | Same day–1 week | None | Partly |
| Cleaning services | Same day–1 week | Low | No |
| Babysitting | Same day–1 week | Low | Sometimes |
| Pet sitting/dog walking | 1–7 days | Low | Sometimes |
| Freelance services | 1 day–several weeks | Low | Yes |
| Virtual assistant work | Several days–weeks | Low | Yes |
| Tutoring | 1–14 days | Low | Yes |
| Delivery work | Several days+ | Low–moderate | No |
| Event staffing | Days–weeks | Low | No |
| Temp work | Days–weeks | Low | Sometimes |
| UGC creation | Days–weeks | Low | Yes |
| Photography | Days–weeks | Moderate | Partly |
| Beauty services | Days–weeks | Varies | Sometimes |
| Resume/LinkedIn help | Days–weeks | Low | Yes |
| Social media management | Days–weeks | Low | Yes |
| Online research studies | Varies | None | Yes |
| User testing | Varies | None | Yes |
| Rent unused space | Days–weeks | Low | Yes |
| Resell items | Days–weeks | Moderate | Partly |
| Meal prep/baking | Varies | Moderate | Yes |
| Personal organizing | Days–weeks | Low | No |
| Errand services | Days–weeks | Low | No |
| Consulting | Days–weeks | Low | Yes |
| Remote customer support | Weeks | Low | Yes |
| Digital products | Weeks+ | Low | Yes |
Actual earnings and payout times vary by location, demand, experience, expenses, platform rules, and payment processing.
1. Sell Things You Don’t Use
If you need money immediately, start inside your home.
Clothing, furniture, electronics, exercise equipment, handbags, tools, collectibles, baby gear, kitchen appliances, and unopened products can all have resale value.
For faster sales:
- Photograph items in natural light.
- Include dimensions, condition, model numbers, and flaws.
- Check comparable local listings before pricing.
- Price slightly below similar items when speed matters more than maximizing profit.
- Bundle inexpensive items together.
Local sales can be especially useful when you need cash quickly because they eliminate shipping delays.
For personal safety, arrange exchanges in well-lit public locations when practical and avoid unnecessarily sharing your home address.
2. Offer House Cleaning
Cleaning is one of the simplest local services to start because customers immediately understand what they’re buying.
Instead of advertising yourself vaguely as a cleaner, create a specific offer such as a two-hour apartment reset, move-out cleaning, kitchen deep clean, or weekly maintenance service.
Clear packages make purchasing easier.
Ask customers to provide photographs or a description of the property before giving a firm quote. A “small apartment” can mean very different amounts of work.
3. Babysit or Provide Childcare
Parents frequently need help for evenings, weekends, appointments, school closures, and date nights.
If you already have childcare experience, relevant certifications, teaching experience, or strong local references, make those credentials visible.
Trust is the product as much as your time is.
Never exaggerate your experience, and check local licensing or registration requirements if you plan to turn occasional babysitting into regular childcare.
4. Walk Dogs or Pet Sit
Pet owners need walkers, drop-in visits, overnight care, feeding, transportation, and vacation coverage.
This can work particularly well if you have a flexible daytime schedule.
Start with people who already have a reason to trust you—neighbors, coworkers, friends, or local community groups—and ask satisfied clients for referrals.
5. Sell a Freelance Skill
Freelancing becomes much faster when you stop presenting yourself as someone who can “do anything.”
Sell one defined result.
Examples include:
- Copyediting a 1,500-word article.
- Designing five social media graphics.
- Creating a PowerPoint presentation.
- Editing short-form video.
- Writing product descriptions.
- Building a spreadsheet dashboard.
- Proofreading resumes.
- Translating documents.
- Cleaning up a company’s email newsletter.
A small, concrete offer is easier for a new client to purchase than an open-ended consulting arrangement.
6. Become a Virtual Assistant
Entrepreneurs and small businesses routinely need help with inboxes, calendars, research, spreadsheets, data entry, customer follow-up, travel planning, and administrative work.
Avoid marketing yourself simply as a “VA.”
A stronger offer is specific: “I help real estate agents organize leads and appointments” or “I provide five hours of weekly administrative support to independent consultants.”
Specialization can make you easier to hire and easier to refer.
7. Tutor Online or Locally
Tutoring can generate income quickly if you already have knowledge people actively pay to learn.
Potential subjects extend beyond school mathematics and English. You might teach conversational languages, standardized-test preparation, music, software, accounting, professional writing, or job-interview skills.
Parents and students usually care about outcomes. State exactly what you can help someone improve.
8. Take Delivery or Shopping Gigs
Food delivery, grocery shopping, package delivery, and similar gig work can provide relatively quick access to paid work where services operate.
But calculate your net earnings rather than looking only at gross pay.
Subtract fuel, vehicle wear, parking, insurance implications, taxes, and unpaid driving time. A shift that appears profitable can look very different after expenses.
9. Work Events
Caterers, conferences, weddings, festivals, sporting events, promotional agencies, and venues regularly need temporary workers.
Jobs may include registration, serving, setup, coat check, brand promotion, guest assistance, or cleanup.
Event work can be useful when you want occasional shifts without committing to a recurring schedule.
10. Register With Temporary Staffing Agencies
Temp agencies can be overlooked by people searching online for side hustles.
Businesses use staffing firms for receptionists, administrators, warehouse workers, customer-service representatives, event employees, bookkeepers, and other temporary roles.
Have a clean resume ready and respond quickly when an agency contacts you. Availability can influence who gets offered short-notice assignments.
11. Create User-Generated Content for Brands
User-generated content, or UGC, is promotional content designed to look and feel like content from an ordinary customer.
You don’t necessarily need a massive social following. Brands may pay creators for the content itself rather than access to their audience.
A basic portfolio can include sample product demonstrations, testimonials, unboxings, tutorials, or lifestyle clips using products you already own.
Treat this as commercial work. Agree in writing on deliverables, revisions, usage rights, deadlines, and compensation.
12. Offer Photography Sessions
If you already own suitable equipment and know how to use it, photography can generate quicker income than building an elaborate photography company.
Consider smaller, easy-to-book services:
- Professional headshots
- Dating-profile photos
- Graduation photos
- Family mini sessions
- Product photos
- Pet portraits
- Real-estate photography
Require a clear booking agreement and communicate what the client will receive.
13. Monetize Beauty Skills You Already Have
Hair styling, makeup, nail services, brows, lashes, and similar services can command meaningful rates—but regulations matter.
Some services require professional licenses, sanitation procedures, insurance, or approved premises depending on where you live.
Don’t treat beauty work as an informal cash shortcut if local law requires professional credentials.
If you’re already qualified, weddings, special events, photography sessions, and referral clients can create additional income.
14. Write Resumes and Optimize LinkedIn Profiles
Professionals changing jobs often need help translating their experience into strong resumes, cover letters, and profiles.
This is best suited to someone who already understands professional writing, hiring, recruiting, or a specific industry.
Don’t guarantee interviews or job offers. Sell the quality of your work, not an outcome you cannot control.
15. Manage Social Media for a Small Business
A local restaurant, salon, fitness studio, tradesperson, consultant, or shop may need help maintaining its social channels without hiring a full-time marketer.
Offer a small starter package instead of an enormous monthly strategy.
For example, you might provide a fixed number of posts, captions, short videos, or scheduled updates.
Define whether the client supplies photography and whether community management—such as responding to comments—is included.
16. Participate in Legitimate Research Studies
Universities, research organizations, and market-research companies recruit participants for interviews, surveys, product studies, and focus groups.
Compensation can vary widely, and opportunities are inconsistent.
Treat research participation as occasional supplemental income rather than a dependable salary.
Be cautious with anyone requesting sensitive financial information unrelated to legitimate payment or research requirements.
17. Test Websites and Apps
Companies pay users to evaluate websites, prototypes, apps, and purchasing experiences.
During a typical usability test, you may be asked to complete tasks and explain what you’re thinking while navigating the product.
The major limitation is volume. Qualification depends on demographics and research needs, so this is rarely dependable enough to solve a large cash shortage by itself.
18. Rent Out Space You Aren’t Using
Unused parking, storage space, equipment, or—where permitted—a spare room can potentially produce income.
Before listing anything, review lease restrictions, homeowners association rules, insurance coverage, local regulations, taxes, and security implications.
Revenue is only worthwhile if you’re comfortable with the access you’re granting.
19. Resell Undervalued Items
Reselling can work, but it’s fundamentally different from selling things you already own.
You’re risking capital.
Start small. Learn one product category, understand actual sold prices, calculate marketplace fees and shipping, and avoid purchasing inventory simply because something appears discounted.
The money is made when the purchase price leaves enough margin—not when the listing goes live.
20. Sell Food or Meal-Prep Services
If you’re known for a particular baked good, meal, dessert, or specialty cuisine, local customers may be willing to pay for it.
Food businesses can be regulated even when operated from home.
Check applicable cottage-food, food-safety, labeling, allergy, business-registration, and delivery requirements before selling.
21. Become a Professional Organizer
Busy households may pay for help organizing closets, kitchens, garages, home offices, paperwork, or moving projects.
This service works best when you sell a result rather than an hourly block of unspecified labor.
“Three-hour closet reset” is easier to understand than “general organizing.”
Protect client privacy. An organizer may see financial records, medications, personal correspondence, valuables, and other sensitive possessions.
22. Run Errands for Busy People
Older adults, new parents, disabled clients, professionals, and people recovering from illness may need legitimate help with groceries, returns, pickups, waiting for contractors, or other errands.
Set boundaries from the beginning.
Clarify mileage, reimbursement, purchase limits, cancellations, and whether clients must prepay expenses.
Never use your own money for large client purchases unless the arrangement is secure and documented.
23. Sell Consulting Based on Your Career Experience
One of the most overlooked answers to how to make money fast as a woman is selling knowledge you’ve already spent years acquiring.
A bookkeeper can help a small business clean up records. A recruiter can offer interview coaching. A project manager can organize a launch. A designer can review a website.
You don’t need a 40-page business plan before landing your first client.
Create one narrowly defined paid session or project, contact people in your existing professional network, and solve a problem you already understand.
24. Apply for Remote Customer-Support Work
Remote support positions aren’t usually same-day money, but they can provide more stability than piecing together small gigs.
Roles may involve phone, email, chat, sales support, scheduling, or technical assistance.
Search directly on legitimate employer career pages and established job boards. Be skeptical of recruiters who interview only through messaging apps, send unexpected checks, or ask you to buy equipment through a specific vendor.
25. Create a Simple Digital Product
Digital products aren’t the fastest solution when you need money tonight, but they can turn knowledge you’ve already developed into an asset you can sell repeatedly.
Examples include templates, checklists, printable planners, worksheets, spreadsheet systems, lesson materials, or professional resources.
The important question isn’t, “What can I make?”
It’s, “What small problem do people already pay to solve?”
Validate demand before spending days creating a large product.
How to Make $100 Fast
If your immediate goal is your first $100, combining several small ideas can be faster than waiting for one perfect opportunity.
For example, you could sell an unused item, complete a local cleaning or organizing job, and offer a skill-based service to someone in your existing network.
Prioritize certainty over novelty.
Someone who already knows Excel is usually better off selling spreadsheet help than spending three days learning an unfamiliar side hustle from social media.
How to Make $500 Fast
A $500 target usually requires a higher-value transaction or several paid jobs.
Look for assets worth selling and services where customers already spend $100 or more per transaction.
That might mean several tutoring sessions, a weekend of event work, a freelance project, multiple cleaning appointments, photography sessions, consulting, or selling higher-value belongings.
Trying to reach $500 through pennies-per-task apps is generally inefficient.
How to Make Money Fast From Home as a Woman
Working from home can reduce commuting costs and provide more flexibility, particularly if transportation, disability, caregiving, or childcare affects when you can work.
The strongest remote options typically rely on skills rather than tiny online tasks.
Good candidates include freelance writing, bookkeeping, design, virtual assistance, tutoring, customer support, consulting, resume writing, social media management, video editing, and UGC production.
When choosing between them, ask:
What can I credibly sell this week without needing weeks of training first?
That question often produces a better answer than searching for the highest-paying side hustle on the internet.
A 24-Hour Plan to Start Making Money
Hour 1: Calculate the Actual Amount You Need
Replace “I need money” with a concrete target.
Do you need $75 by tomorrow, $300 this week, or an additional $800 every month?
Different deadlines require different strategies.
Hours 2–3: Inventory What You Can Monetize
Write down your available assets:
- Items you could sell.
- Skills you’ve used professionally.
- Tasks friends routinely ask you to help with.
- Transportation or equipment you own.
- Hours you’re genuinely available.
- People who may already trust you enough to hire or refer you.
Don’t spend this stage inventing a completely new identity.
Hours 4–6: Create One Clear Offer
Use a simple formula:
I help [type of customer] achieve [specific result] for [clear price or pricing method].
For example:
I provide two-hour apartment cleaning sessions for busy professionals in my area.
Specificity removes friction.
Hours 6–12: Put the Offer in Front of Buyers
Start where trust already exists: your personal network, professional contacts, neighborhood communities, previous clients, alumni groups, or relevant marketplaces.
Don’t send a vague message saying you’re “looking for opportunities.”
Explain exactly what you’re offering and who it is for.
Hours 12–24: Follow Up and Improve
If nobody responds, diagnose the problem before dropping your price.
Your offer may be unclear, your audience may be wrong, or there may be too little evidence that you can deliver.
Change one variable at a time.
The Best Options Based on Your Situation
If You Need Money Today
Focus on selling possessions or finding immediate local work.
Starting a YouTube channel, ecommerce store, or blog does not solve a same-day cash problem.
If You Need Money This Week
Combine short-term services with temporary work.
Cleaning, pet care, childcare, event shifts, tutoring, freelancing, organizing, delivery work, and temp assignments may be more realistic than passive-income ideas.
If You Need Money Every Month
Move toward repeatable services or employment.
A recurring cleaning client, weekly tutoring student, monthly social-media client, part-time customer-support role, or ongoing freelance contract can be considerably more predictable than continuously chasing one-off gigs.
If You Have Children or Caregiving Responsibilities
Compare earnings with the true cost of working, including childcare, commuting, food, and scheduling constraints.
A lower-paying remote project can sometimes leave you with more usable income than a higher-paying shift requiring substantial childcare and transportation expenses.
If You Don’t Have a Car
Concentrate on remote skills, neighborhood services, tutoring, babysitting, pet care, online assistance, consulting, digital products, or work reachable by public transportation.
You don’t need to force a delivery-based side hustle simply because it appears frequently in search results.
How Women Can Make Money Without Compromising Personal Safety
The mechanics of earning money are not inherently different for women, but personal-safety considerations can affect which opportunities are practical.
When working with unfamiliar clients:
- Keep initial communication on established platforms when possible.
- Avoid publishing your home address unnecessarily.
- Meet buyers in public places when appropriate.
- Tell someone where you’re going for in-person work.
- Verify clients before entering private residences.
- Use separate business contact information if you don’t want strangers to have your personal number.
- Keep written records of agreements and payments.
- Leave situations that materially differ from what was agreed.
Higher pay does not justify ignoring serious safety concerns.
Money-Making Scams to Avoid
Urgency makes people easier targets for fraud. Be particularly cautious when someone promises unusually easy money while requiring you to send money first.
Fake Check Scams
A supposed employer or client sends you a check, tells you to deposit it, then asks you to forward part of the money elsewhere.
The check can later be reversed, leaving you responsible for the money you sent.
Pay-to-Work Schemes
Legitimate businesses can have normal professional expenses, but a stranger offering employment should not need you to purchase expensive training, starter kits, cryptocurrency, gift cards, or special software from them before you can be paid.
Package Reshipping Jobs
Be highly skeptical of jobs asking you to receive packages at home and forward them elsewhere. These arrangements can involve stolen merchandise or fraudulent transactions.
Guaranteed-Income Claims
No legitimate side hustle can guarantee that you’ll earn thousands of dollars immediately with little effort.
Treat screenshots of extraordinary earnings as advertising, not proof of what an average beginner can expect.
Recruitment-First Business Models
If the opportunity seems more focused on recruiting participants or buying inventory than selling something customers independently want, investigate carefully before paying anything.
Urgent financial pressure is a particularly poor time to take speculative business risks.
Common Mistakes That Slow Down Your Earnings
Trying Five Side Hustles at Once
More opportunities do not automatically create more income.
Choose one immediate-money strategy and one potentially repeatable strategy. Give each enough attention to determine whether it works.
Spending Before You’ve Earned
You probably don’t need a logo, paid course, premium website, elaborate software stack, or large supply order to earn your first dollar.
Get a customer before optimizing the business around customers you don’t have.
Charging Only for Your Time
When practical, package an outcome.
Customers may find “$125 for a move-out kitchen clean” easier to evaluate than an open-ended hourly rate.
Ignoring Expenses and Taxes
Revenue is not profit.
Track mileage, supplies, marketplace fees, payment-processing fees, advertising, equipment, refunds, and other legitimate business costs. Understand the tax obligations that apply where you live.
Accepting Work Without Defining the Scope
Agree on the deliverable, price, deadline, revision policy, expenses, and payment terms before beginning substantial work.
A five-minute written agreement can prevent hours of unpaid work later.
Can You Make Money Fast Online?
Yes, but “online” doesn’t automatically mean “fast.”
Remote freelancing can pay well when you already possess a valuable skill. Online surveys and microtasks may be easier to enter but generally have a much lower ceiling and inconsistent availability.
A useful rule is:
The fewer barriers to entry an online job has, the more competition you’re likely to face.
Instead of searching endlessly for websites that distribute small tasks, consider selling a specific skill directly to a specific buyer.
What Is the Most Profitable Side Hustle for Women?
There isn’t one universal answer.
Profitability comes from the intersection of demand, skill, pricing power, expenses, and repeat business—not gender.
A woman with bookkeeping experience may earn more from financial administration than from pet sitting. A teacher may have more leverage tutoring. A videographer may be better positioned for UGC or editing.
Your existing competence is an economic advantage. Use it before investing months in learning a fashionable side hustle.
Should You Start a Business When You Need Money Quickly?
Sometimes, but distinguish between earning money and building a business.
If rent is due in four days, your priority is probably cash flow. Sell something, take paid work, or provide an immediately marketable service.
Once the immediate pressure is lower, you can systemize what worked: raise rates, build recurring clients, improve marketing, purchase insurance, register a business where appropriate, and create longer-term income streams.
Trying to build the perfect company before making your first sale often delays the thing that matters most: getting paid.
Frequently Asked Questions
How can a woman make money fast with no money?
Start with options that use assets you already have: selling unused belongings, cleaning, babysitting, pet sitting, tutoring, freelance services, organizing, virtual assistance, or consulting based on existing skills.
Avoid business models requiring inventory, advertising, or expensive training when you have no capital to risk.
How can a woman make money fast without a job?
You can sell possessions, provide local services, take freelance projects, participate in temporary gigs, tutor, pet sit, clean homes, create UGC, or offer professional expertise.
For consistent income, however, consider combining immediate gigs with a search for recurring clients or employment.
How can I make money fast on my phone?
A phone can help you list items for sale, communicate with freelance clients, manage social media, apply for gigs, coordinate pet care, participate in qualifying research, or create simple UGC.
Be wary of apps implying that repetitive tapping or watching advertisements will produce substantial income.
What’s the easiest way to make money fast?
The easiest option is usually monetizing something you already possess.
Selling an unused item requires less setup than developing a new skill. Providing a service you’ve performed for years is usually easier than starting an unfamiliar online business.
Can I make money without showing my face online?
Yes.
Writing, editing, bookkeeping, virtual assistance, spreadsheet work, graphic design, coding, research, tutoring without public content, customer support, translation, and many digital products don’t require building a public personal brand.
Final Thoughts on How to Make Money Fast as a Woman
The best answer to how to make money fast as a woman is rarely a secret website or overnight business model. Fast, legitimate income usually comes from selling something you already own, solving an urgent problem for someone nearby, or monetizing a skill you already know.
Start with the shortest path to your first payment. Protect your personal information, calculate your real profit, avoid opportunities that require risky upfront spending, and turn the methods that work into repeatable income.
Your next move is simple: choose one method you can act on today, set a specific earnings target, and put a concrete offer in front of potential buyers before spending money building anything.
Searching for myusfinance financial tools usually reflects a mix of informational and commercial intent. You may be trying to understand what financial products are available, compare options for borrowing or improving your credit, or decide whether the platform is appropriate before sharing personal information.
One important distinction comes first: the financial platform currently operating at MyUSAFinance.com uses the brand name MyUSAFinance. Its website functions primarily as a financial-products marketplace rather than a traditional budgeting app, bank, or direct lender. It connects consumers with third-party providers across areas such as personal loans, credit cards, credit monitoring, and debt-relief services.
This guide explains what these tools actually do, how to evaluate the offers you see, and which details deserve the closest attention before you apply.
Quick Facts About myusfinance financial tools
| Feature | What to Know |
|---|---|
| Platform type | Financial-product comparison and connection service |
| Direct lender? | No |
| Core categories | Personal loans, credit cards, credit-score services, debt relief |
| Cost to use platform | MyUSAFinance states that its connection service is free |
| Loan decisions | Made by independent lenders |
| Loan availability | Depends on lender, applicant, state, and other eligibility factors |
| Credit monitoring | Third-party credit-related offers may be available |
| Debt solutions | May include consolidation, settlement, management, or related services |
| Minimum age | Users must generally be at least 18 |
| Key consideration | Compare the third-party provider’s final terms—not simply the marketplace listing |
MyUSAFinance explicitly states that it does not make lending or credit decisions. Instead, it connects consumers with independent financial providers whose eligibility rules, fees, rates, and terms may differ.
What Are MyUSFinance Financial Tools?
The phrase myusfinance financial tools can be misleading if you expect calculators, expense trackers, investment dashboards, or a bank-account management app.
The MyUSAFinance platform is more accurately described as a financial marketplace and matching service. Its primary purpose is to help users explore financial products and potentially connect with third-party companies offering them.
The main categories promoted by the platform include:
- Personal loans
- Credit card offers
- Credit-score and monitoring services
- Debt-relief solutions
- Additional financial and consumer offers through partner providers
The website emphasizes shopping and comparing financial options rather than managing every aspect of a household budget inside one dashboard.
That difference matters. A marketplace helps you find products; a personal finance management tool generally helps you track and control your existing money.
How MyUSAFinance Works
The basic process varies according to the financial product you choose, but the overall model is straightforward.
1. Choose the Financial Product You Need
Users can begin by selecting a category such as loans, cards, credit monitoring, or debt relief.
This is more effective than browsing randomly. Start with the financial problem you actually need to solve.
For example:
- Need to finance a specific expense? Explore personal-loan options.
- Want rewards or access to revolving credit? Compare credit cards.
- Concerned about your credit profile? Review credit-monitoring tools.
- Struggling with multiple unsecured debts? Investigate debt-relief alternatives.
2. Provide Information Relevant to the Offer
Some marketplace sections request information such as state, estimated credit score, income range, desired loan amount, or email address to personalize potential offers.
A loan request may require considerably more personal information during the matching process.
Never treat this step casually. Financial applications may involve sensitive identity and financial data.
3. Review Available Providers or Offers
The platform may present third-party services that potentially match your profile or selected category.
At this point, the most important work begins.
Do not compare offers only by headline claims such as:
- “Fast funding”
- “Low monthly payment”
- “All credit types considered”
- “No upfront fee”
Instead, compare the full economics and obligations behind each offer.
4. Continue With the Third-Party Provider
If you select an offer, you may continue to an independent lender or service provider.
The third party—not MyUSAFinance—typically determines approval, pricing, qualification requirements, and final contractual terms.
5. Read the Final Agreement Before Accepting
A marketplace can help narrow your choices, but the final agreement controls what you actually pay and what obligations you accept.
Never assume that a rate, payment, eligibility statement, or benefit mentioned earlier in the shopping process automatically becomes part of your final contract.
Personal Loan Tools
Personal loans are one of the most prominent parts of the MyUSAFinance offering.
The site says users can submit a loan request and potentially connect with lenders from its network. Its published disclosures emphasize that submitting information does not guarantee approval, while final loan decisions and terms are determined by providers.
What to Compare Before Choosing a Personal Loan
The interest rate alone is not enough.
Evaluate:
| Loan Factor | Why It Matters |
|---|---|
| APR | Represents borrowing cost more comprehensively than the interest rate alone |
| Origination fee | May reduce the amount you actually receive |
| Monthly payment | Determines whether the loan fits your cash flow |
| Loan term | Longer terms may lower payments but increase total borrowing cost |
| Total repayment | Shows the true dollar cost over the life of the loan |
| Late-payment fees | Important if your monthly budget is tight |
| Prepayment rules | Determine whether early payoff creates extra costs |
| Funding time | Important only if the expense is genuinely urgent |
| Lender identity | You should know exactly which company is offering the loan |
MyUSAFinance publishes an illustrative example involving an origination fee, APR, monthly repayment, and total interest, reinforcing why borrowers need to consider the complete cost rather than the requested principal alone.
A Better Way to Compare Two Loans
Suppose Loan A offers the lower monthly payment but requires repayment for five years.
Loan B costs slightly more each month but finishes in three years.
Loan A may initially appear more affordable, yet Loan B could cost substantially less overall.
For every loan, write down four numbers:
- Amount deposited into your account
- Monthly payment
- Number of payments
- Total amount repaid
That simple calculation prevents one of the most common borrowing mistakes: choosing the smallest payment instead of the best overall deal.
Credit Card Comparison Tools
Another major component of myusfinance financial tools is credit-card discovery.
The platform promotes the ability to explore cards based on features such as rewards, cash back, travel benefits, and other characteristics.
How to Compare Credit Cards Properly
The “best” card depends on how you intend to use it.
If You Pay the Balance in Full
Focus primarily on:
- Annual fee
- Cash-back rate
- Rewards categories
- Welcome offer
- Redemption restrictions
- Travel protections
- Foreign transaction fees
A card with a strong rewards program may make sense if you never carry interest-bearing balances.
If You Expect to Carry a Balance
Prioritize:
- Purchase APR
- Introductory APR period
- Balance-transfer APR
- Balance-transfer fee
- Penalty APR
- Annual fee
A 2% rewards rate provides little value if you routinely pay much more than that in interest.
If You Are Building Credit
Look at:
- Approval requirements
- Annual fee
- Reporting to major credit bureaus
- Security-deposit requirements
- Credit-limit policies
- Upgrade options
- Other recurring charges
Do not assume every product marketed toward consumers with limited or damaged credit is inexpensive.
Credit Score and Monitoring Tools
MyUSAFinance also lists third-party services related to credit scores and monitoring. Its marketplace has included products offering features such as credit-score access, credit tracking, reports, or alerts.
Credit monitoring can be useful, but it is important to understand its limitations.
What Credit Monitoring Can Do
Depending on the provider, a monitoring service may help you:
- Watch for changes in your credit file
- Track score movements
- Identify newly reported accounts
- Detect suspicious credit activity
- Receive alerts after certain changes
- Review factors affecting your credit profile
What Credit Monitoring Cannot Do
Monitoring does not automatically:
- Remove legitimate negative information
- Increase your score
- Eliminate debt
- Guarantee loan approval
- Prevent every form of identity theft
Think of monitoring as an early-warning and awareness tool, not a repair button.
Before Paying for Credit Monitoring
Check exactly what you receive.
Ask:
- Which credit bureau or bureaus are monitored?
- How frequently are reports updated?
- Is the displayed score the same scoring model lenders commonly use?
- Is identity monitoring included?
- Is there a monthly subscription?
- Does the price increase after an introductory period?
- How do you cancel?
A free score can be useful. A recurring subscription should provide enough additional value to justify its cost.
Debt-Relief Tools and Offers
Debt relief requires more careful evaluation than almost any other category because different solutions can have very different consequences.
MyUSAFinance’s marketplace includes debt-related offers, and its broader site describes possible approaches such as consolidation, settlement, and debt-management solutions.
These terms are not interchangeable.
Debt Consolidation
Consolidation generally means replacing multiple debts with a new loan or credit product.
It can make sense when:
- The new interest rate is lower
- Fees are reasonable
- The new payment fits your budget
- You stop accumulating replacement credit-card debt
Consolidation changes the structure of debt. It does not erase it.
Debt Management
A debt-management plan may involve structured repayment arrangements, often with creditor negotiations handled through a third party.
Before enrolling, understand:
- Program fees
- Expected payment schedule
- Which creditors participate
- Whether accounts must be closed
- What happens if you miss a program payment
Debt Settlement
Settlement generally aims to resolve debt for less than the full balance.
It can involve significant financial and credit consequences, so consumers should carefully examine fees, creditor policies, potential tax implications, collection risks, and the effect on credit before proceeding.
A promise to “reduce your debt” should never be evaluated without reading what the process actually requires.
MyUSFinance Financial Tools: Pros and Cons
Potential Advantages
Centralized comparison
A marketplace can reduce the amount of time required to discover multiple financial providers individually.
Multiple financial categories
Loans, cards, credit tools, and debt options can be explored from one starting point.
Online access
MyUSAFinance says its services can be accessed through desktop or mobile devices.
No obligation to accept a matched loan
The platform states that consumers can reject a loan offer rather than being required to accept it.
Marketplace service is free to consumers
MyUSAFinance states that it receives compensation from partners rather than charging users for being connected with lenders.
Potential Drawbacks
It is not a direct lender
A marketplace cannot guarantee the rate, approval decision, or terms a third-party lender will provide.
Offers may involve marketing relationships
The platform’s privacy disclosures state that submitted information can be shared with certain lenders, financial institutions, service providers, marketers, or other parties depending on the interaction.
Partner offers can vary widely
Products shown within the same marketplace may have very different costs, qualification standards, and terms.
Not a full money-management dashboard
Consumers looking specifically for expense tracking, bank syncing, net-worth tracking, or detailed budgeting may need a separate financial-management application.
Privacy: What You Should Know Before Submitting Information
This is one of the most important sections for anyone considering the platform.
MyUSAFinance’s privacy policy states that a loan request may involve information such as a Social Security number, driver’s-license information, employment details, age, and ZIP code. The policy also describes circumstances in which information can be provided to third parties for product matching, marketing, analytics, operational activities, and related purposes.
That does not automatically make the service inappropriate. It means you should understand the data exchange before completing a form.
Before You Click Submit
Use this checklist:
- Confirm that you are on the correct website.
- Read the current privacy policy.
- Understand who may receive your information.
- Check whether you are consenting to phone, email, or text communications.
- Determine whether your information may be used for marketing.
- Read the selected provider’s separate privacy policy.
- Avoid submitting applications casually to “see what happens.”
Financial comparison becomes less valuable if you create unnecessary exposure of sensitive personal information.
Does MyUSAFinance Check Your Credit?
MyUSAFinance’s disclosure says the platform itself does not pull your credit when acting as the matching service, but participating lenders may verify creditworthiness and review information through credit bureaus or other reporting sources after receiving a request.
This distinction is important.
Before continuing with any lender, determine whether the next step involves:
- No credit inquiry
- A soft inquiry
- A hard credit inquiry
A hard inquiry can affect your credit profile, while a soft inquiry generally does not have the same scoring impact.
Do not rely solely on general marketplace wording. Confirm the inquiry policy directly with the provider handling your application.
Who Should Consider Using These Financial Tools?
The platform may be useful for someone who:
- Wants one place to begin comparing financial products
- Needs to explore multiple potential loan providers
- Is researching credit-card options
- Wants access to third-party credit-monitoring offers
- Is comparing possible debt-relief approaches
- Understands that the marketplace itself is not the lender
- Is willing to investigate each provider independently before accepting an offer
Who May Need a Different Type of Tool?
Consider another category of service if your primary objective is:
- Creating a monthly household budget
- Automatically categorizing transactions
- Tracking investments
- Calculating net worth
- Managing retirement projections
- Tracking business expenses
- Filing taxes
- Receiving individualized investment advice
Those tasks require financial-management, investing, accounting, or planning tools rather than simply a marketplace for financial products.
A Practical Framework for Evaluating Any Financial Offer
Do not start by asking, “Can I get approved?”
Start by asking, “Does this improve my financial position?”
Use the following five-step test.
Step 1: Define the Problem
Write down exactly what you are trying to achieve.
For example:
Replace $8,000 of high-interest credit-card debt with a lower-cost fixed repayment plan.
That is much more useful than simply writing:
Get a loan.
Step 2: Calculate the Current Cost
Determine what your existing situation costs each month and in total.
For debt, record:
- Current balance
- Interest rate
- Minimum payment
- Estimated payoff period
- Fees
Without a baseline, you cannot tell whether a new product is actually better.
Step 3: Compare at Least Three Options
One offer tells you what is available.
Multiple comparable offers tell you whether it is competitive.
Compare similar products using the same criteria.
Step 4: Measure Total Cost
Never evaluate financing using only the payment amount.
Calculate:
Total repayment = monthly payment × number of payments + applicable upfront costs
Then compare that amount with other alternatives.
Step 5: Read the Contract
The final provider agreement matters more than the advertisement.
Verify:
- APR
- Fees
- Payment schedule
- Automatic-payment terms
- Late fees
- Cancellation provisions
- Prepayment rules
- Data-sharing consent
- Dispute provisions
Save a copy before completing the transaction.
Common Mistakes to Avoid
Choosing Speed Over Cost
“Funds as soon as the next business day” can sound attractive during an emergency.
But receiving expensive credit quickly can turn a temporary shortage into a long-term repayment problem.
Applying Without Knowing Your Budget
Calculate the maximum payment you can realistically afford before shopping for credit.
Never work backward by taking the lender’s proposed payment and trying to force it into your budget.
Focusing Only on Approval Odds
Approval is not the goal.
Affordable repayment is.
A loan that you qualify for but cannot comfortably repay is not a financial solution.
Ignoring Fees
Origination fees, annual fees, balance-transfer fees, subscription costs, and other charges can materially change a product’s value.
Assuming Every Marketplace Listing Is Equivalent
A comparison platform can display very different types of companies.
Evaluate the actual provider, not simply the website that introduced you.
Confusing Credit Monitoring With Credit Improvement
Knowing your credit score is useful, but monitoring alone does not create better credit.
Improvement generally depends on the underlying factors affecting your credit profile, such as payment history, debt levels, account age, and other scoring inputs.
How to Get More Value From MyUSFinance Financial Tools
Use the marketplace as the beginning of your research, not the end.
A disciplined workflow looks like this:
- Identify the exact financial problem.
- Decide which product category could address it.
- Review several offers.
- Record rates, fees, terms, and provider names.
- Visit each provider’s disclosures.
- Check whether there will be a credit inquiry.
- Calculate total cost.
- Review privacy and communication consent.
- Compare the offer with alternatives outside the marketplace.
- Apply only when the economics make sense.
This method takes slightly longer than clicking the first attractive offer, but it produces a far better financial decision.
Questions to Ask Before Accepting Any Offer
For loans:
- What is the APR?
- What amount will actually reach my bank account?
- What is the total repayment?
- Is there an origination fee?
- Can I repay early without penalty?
- When is the first payment due?
For credit cards:
- What is the ongoing APR?
- Is there an annual fee?
- Does an introductory rate expire?
- How are rewards redeemed?
- Are there foreign transaction fees?
For credit monitoring:
- Is it free permanently or temporarily?
- Which bureau data is included?
- Is there a recurring subscription?
- How do I cancel?
For debt relief:
- What type of program is this?
- How are fees calculated?
- What happens to my existing accounts?
- Could creditors continue collection activity?
- What happens if the program fails?
- What are the possible credit consequences?
If a provider cannot give straightforward answers, do not rush into the product.
Frequently Asked Questions
Is MyUSAFinance a lender?
No. The company states that MyUSAFinance is not a lender and does not make lending or credit decisions. It connects users with independent third-party providers.
Are myusfinance financial tools free?
MyUSAFinance states that its service for connecting consumers with lenders is free and that it receives compensation from lending partners. Individual third-party products may still involve interest, subscriptions, annual fees, service fees, or other costs.
What financial tools does MyUSAFinance provide access to?
The website prominently features personal loans, credit cards, credit-score services, and debt-relief solutions, along with additional marketplace offers from third parties.
Can MyUSAFinance guarantee loan approval?
No. Its disclosures state that submitting information does not guarantee approval. Individual providers make their own lending decisions.
Can I compare different loan amounts?
The site’s loan-offer interface has displayed multiple requested loan-amount ranges along with inputs such as state, estimated credit score, and monthly income. Availability and actual offers remain dependent on individual providers and eligibility.
Will using the platform affect my credit score?
MyUSAFinance states that it does not itself pull your credit as part of its matching role, but lenders may review your creditworthiness. Verify whether a particular provider will perform a soft or hard inquiry before proceeding.
Is MyUSAFinance a budgeting app?
Its primary website is better characterized as a financial-product marketplace. Users specifically seeking automatic budgeting, transaction categorization, investment tracking, or net-worth management may need a dedicated personal finance application.
Should I accept the first offer I receive?
Usually, no. The value of a marketplace comes from comparison. Evaluate several realistic options and compare APR, fees, repayment terms, total cost, provider reputation, and contractual requirements before choosing.
Final Verdict on myusfinance financial tools
myusfinance financial tools are most useful when viewed as a gateway for exploring financial products rather than as an all-in-one money-management system.
MyUSAFinance can provide a convenient starting point for consumers researching personal loans, credit cards, credit monitoring, and debt-relief options. The platform itself, however, does not determine the final price or approval terms of products offered by independent providers.
The best approach is simple: use the marketplace to discover possibilities, then evaluate each provider independently. Compare total costs instead of headline payments, understand how your information may be used, verify credit-check requirements, and read every final agreement before accepting it.
Used that way, myusfinance financial tools can support a more informed comparison process—while keeping the final financial decision where it belongs: in your hands.


sama neview 2851a: Specs, Airflow & Buying Guide

HP L2335 Monitor Explained: Features, Setup & Buying Advice

NZXT Kraken X60 Review: Specs, Performance & Value
-
 Fashion9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Fashion9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Business9 years ago
Uber and Lyft are finally available in all of New York State
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Sports9 years ago
Steph Curry finally got the contract he deserves from the Warriors
-
Sports9 years ago
Phillies’ Aaron Altherr makes mind-boggling barehanded play
-
Entertainment9 years ago
Disney’s live-action Aladdin finally finds its stars
Pingback: kenneth mygreenbucks net